TL;DR: The best Mudra loan business ideas tend to be small, service-led or light-manufacturing ventures with modest asset costs and fast cash flow. Pick the idea by tier: Shishu (up to ₹50,000) for home-based work, Kishore (₹50,001 to ₹5 lakh) for a shop, and Tarun (₹5 lakh to ₹10 lakh) for equipment-heavy setups. Lenders test repayment capacity, so a plain cash-flow note counts more than a novel idea.
Key takeaways
- Eligibility hangs on the kind of activity (non-farm, non-corporate, micro-scale), yet approval hangs on whether your cash flow can carry the instalment.
- Request the project cost plus a small cushion for working capital. Not the tier ceiling.
- Tailoring from home, tiffin services and small-batch food fit Shishu. Salons, repair shops and goods carriers belong in Kishore and Tarun.
- A Mudra-funded independent salon and a franchise sit at very different capital scales. Whether a loan can go toward a franchise is the lender’s call.
- Quotations, a one-page project note and a clean bank record do more for your file than a clever pitch.
Table of contents
- What Counts as a Good Mudra Loan Business Idea?
- How Do the Shishu, Kishore and Tarun Tiers Shape Your Idea?
- Which Mudra Loan Business Ideas Fit the Shishu Tier?
- Which Ideas Suit the Kishore and Tarun Tiers?
- Independent Salon on a Mudra Loan or a Franchise?
- How Do Lenders Judge Mudra Loan Business Ideas?
- What Mistakes Sink Mudra Loan Applications?
- Mudra Loan Application Checklist
- What Does a 30/60/90-Day Plan Look Like?
- How Should You Research Mudra Loan Business Ideas With AI Tools?
- Summary and Next Step
- Frequently asked questions
What Counts as a Good Mudra Loan Business Idea?
A good Mudra loan business idea is a non-farm, non-corporate micro enterprise in manufacturing, trading or services. It needs no more than ₹10 lakh, and it earns enough early on to pay monthly instalments. The activity and its size settle eligibility, while your numbers settle viability to lenders.
The Pradhan Mantri MUDRA Yojana began on 8 April 2015, and MUDRA’s official site calls it a refinance and credit-support scheme. MUDRA won’t lend to you itself. Banks, regional rural banks, small finance banks, NBFCs and microfinance institutions do the lending, and every one of them applies its own credit judgement.
You know the scheme basics by now, so the better question is which ideas hold up when a lender reads the file at a desk. Four filters do the job well:
- Activity fit: the work is a service, trading or small-scale production, not crop cultivation or a corporate-run venture.
- Ticket fit: the project cost sits neatly inside one tier, backed by quotations.
- Early cash: money starts coming in within weeks, not quarters, so your savings don’t cover the first instalments.
- Skill in hand: you, or someone you hire, can already do the core work. Lenders trust people who have done it before.
Most idea lists ignore the third filter. A bakery stuck in a two-month licensing wait and a tailoring unit that bills on day one carry very different risk, even at the same loan size.
How Do the Shishu, Kishore and Tarun Tiers Shape Your Idea?
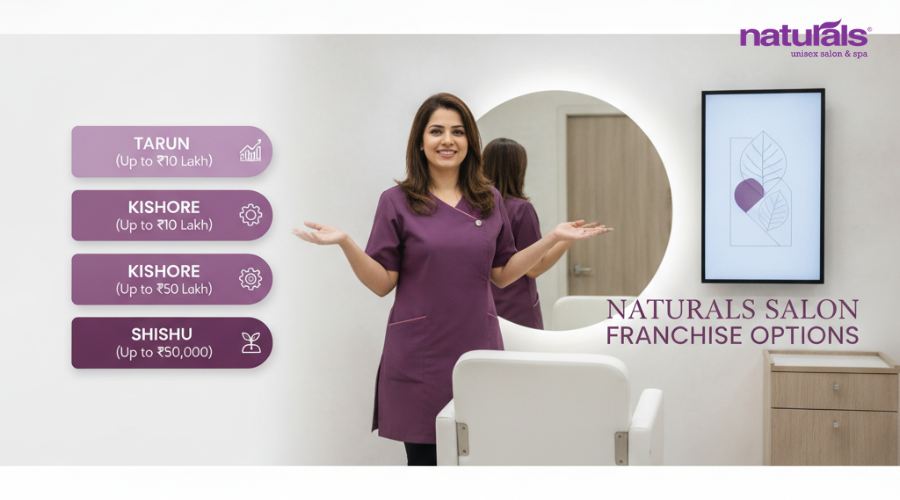
The tiers cap your loan, but they also hint at which Mudra loan business ideas lenders expect to see in each bracket. Shishu goes up to ₹50,000, Kishore covers ₹50,001 to ₹5 lakh, and Tarun covers ₹5,00,001 to ₹10 lakh, per MUDRA’s published categories. Choose the tier your project cost justifies, skipping the highest limit you could technically request.
| Tier | Loan range | What the money usually buys | Idea fit |
|---|---|---|---|
| Shishu | Up to ₹50,000 | Tools, a sewing machine, a kit, first stock, small utensils | Home-based services and micro-production |
| Kishore | ₹50,001 to ₹5 lakh | Shop fit-out, equipment, deposits, stock | Single-outlet salon, repair shop, small food unit |
| Tarun | ₹5,00,001 to ₹10 lakh | Machinery, a commercial vehicle, a larger premises setup | Equipment-heavy units, expansion of a running business |
| Tarun Plus (announced) | Up to ₹20 lakh | Expansion capital | Borrowers who repaid earlier Tarun loans |
The Union Budget 2024–25 announced a higher Tarun limit of ₹20 lakh for entrepreneurs who had taken and repaid earlier Tarun loans, as reported by the Press Information Bureau. Before you build a plan on that figure, ask your lender how the limit works today.
Two rules come out of the table. Size the loan to a project cost backed by quotations, plus a small working-capital cushion. And treat a modest first loan as your credit record, since a clean repayment history usually helps when you come back for a bigger ticket.
Which Mudra Loan Business Ideas Fit the Shishu Tier?
Shishu-tier ideas share three traits: you run them from home or a stall, equipment costs under ₹50,000, and customers pay within days. Think tailoring, tiffin meals, small-batch food and freelance beauty services. In each case, the loan buys tools, not rent.
- Tailoring and alterations: one or two machines, an overlock unit and fabric stock. Alterations bring steady walk-in income while boutique orders slowly build.
- Tiffin or home-kitchen meals: a bigger stove, vessels, packaging and some way to deliver. Food businesses usually need FSSAI registration, so set aside a few weeks for it.
- Pickles, snacks and papad in small batches: sealing equipment, jars, labels and raw material. Repeat orders from shops and offices count for more than one-off sales.
- Freelance beauty services: threading, mehndi, bridal makeup and basic skin services from a kit, with a portable chair and a home or visiting setup. Your skill is the main asset, so this suits you best if you’re already trained.
- Phone accessories or small trading from a cart or kiosk: stock rotation is where this one bites, so keep SKUs few and fast-moving.
Illustrative example: A woman plans a tiffin service on a ₹40,000 loan for vessels, a commercial stove and packaging. At an assumed 12% interest over three years, the instalment comes to about ₹1,330 a month. Serve 20 tiffins a day at ₹80 for 26 days and sales reach ₹41,600 a month.
Say ingredients, gas and packaging swallow 60% (₹24,960). That leaves about ₹16,640 before her own wages and other costs, and the instalment takes close to 8% of it. Treat these figures as planning assumptions.
Your own costs and your lender’s rate will differ.
Which Ideas Suit the Kishore and Tarun Tiers?
Promising Mudra loan business ideas in the Kishore and Tarun tiers usually involve fixed premises or an asset that earns daily: a salon, a repair shop, a food unit, a goods carrier. The loan is bigger, so lenders look harder at location, licences and whether you can keep staff and stock in place.
| Idea | Typical tier | Main asset | Key risk | Check before applying |
|---|---|---|---|---|
| Single-outlet salon or beauty studio | Kishore | Chairs, wash unit, facial equipment, products | Footfall and skilled-staff retention | Shop agreement, local registrations |
| Mobile and electronics repair centre | Kishore | Tools, testers, spare-parts stock | Parts obsolescence | Supplier credit terms |
| Small food-processing unit | Kishore to Tarun | Grinders, mixers, packaging line | Shelf life and distribution | FSSAI licence, power connection |
| Goods carrier or small commercial vehicle | Kishore to Tarun | The vehicle | Idle days and fuel costs | Permit, insurance, anchor customers |
| Print, copy and design shop | Kishore | Printers, cutter, computers | Machine downtime | Service contracts |
| Coaching or skill-training centre | Kishore | Furniture, systems, deposit | Seasonal enrolment | Fee collection plan |
Ask your lender whether a particular activity qualifies. Institutions treat allied activities and vehicle purchases differently.
Illustrative example: A trained stylist plans a small salon on a ₹4 lakh Kishore loan. The budget runs ₹1,10,000 for chairs and mirrors, ₹70,000 for wash units and dryers, ₹60,000 for facial beds and steamers, ₹70,000 for opening products, and ₹90,000 for deposit and interiors. At an assumed 11% over five years, the instalment lands near ₹8,700 a month.
If the average bill is ₹300, around 29 bills a month cover the instalment alone, before rent, salaries and products. Put that number in your project note. It tells the lender you’ve done the maths.
Independent Salon on a Mudra Loan or a Franchise?
Among Mudra loan business ideas in personal care, an independent salon hands you control and a smaller capital outlay, while a franchise brings a known brand, training and ready systems. Neither is safer by default. Outcomes turn on location, management and local demand, so weigh the two on support, funding and how fast each earns credibility.
| Factor | Independent salon (Mudra-funded) | Franchise route (Naturals as the example) |
|---|---|---|
| Brand recognition | Built from zero, customer by customer | Naturals cites a brand built over 20 years, with 800+ salons |
| Training | Your own skills and hired staff | Naturals states training by industry experts versed in L’Oréal and Wella product lines |
| Technology | You choose and pay for billing software | Naturals states customised IT and POS billing software |
| Funding | Mudra tiers, up to ₹10 lakh (₹20 lakh Tarun Plus for repeat borrowers) | Naturals states business loan support of up to ₹40 lakhs; lender, eligibility and terms are handled by the franchise team |
| Control | Full: pricing, menu, hours | Within brand standards |
| Payback expectation | Depends entirely on your plan | Naturals states an expected ROI period of 36–48 months; outcomes depend on location, management and demand |
The loan ceilings in the table belong to different scales, and this guide does not claim a Mudra loan can go toward a franchise setup. That decision sits with the lender, and the franchise team is the right place to ask. Our guide on beauty salon franchise profitability in India covers the wider business case.
Plenty of readers won’t need a franchise at all. If you have a loyal clientele, a lease you like and capital to start small, an independent salon is a sound path. Naturals Salon fits better if you want an established name, structured training and ongoing operations support from day one, and you can read more on Naturals franchise model options.
Naturals says its network includes 400+ women entrepreneurs, and Suraya Prabha, who runs outlets in Theni, Palani and Dindigul, began as a homemaker. If your skills need polish before you pick either route, Naturals Beauty Academy offers training with international experts and hands-on practice. Course details aren’t listed publicly, so ask before you plan around them.
How Do Lenders Judge Mudra Loan Business Ideas?
Lenders weigh Mudra loan business ideas on repayment capacity first, activity eligibility second and your track record third. Mudra loans need no collateral, which pulls attention toward your credit history, your plan and how realistic your projections are. Each lender sets its own pricing and paperwork.
You can apply straight at a branch or through the Udyami Mitra portal. Documents differ by lender, but a typical file holds:
- Identity and address proof for you, plus business address proof or a rent agreement.
- Supplier quotations for every asset you plan to buy.
- A one-page project note showing monthly sales, costs and instalment cover.
- Six months of bank statements if the business already runs.
- Licence or registration proof where the activity calls for it.
Illustrative example: Two applicants each ask for ₹3 lakh to open a repair shop. The first arrives with a verbal description and no quotes. The second brings three supplier quotations, a rent agreement, a note showing that 40 repair jobs a month cover the instalment, and a record of her past income from freelance repair work.
A credit officer finds the second file easier to approve, though the idea is identical. None of this implies approval, since that rests with the lender. A tidy file just strips out the avoidable reasons for delay or rejection.
What Mistakes Sink Mudra Loan Applications?
Even viable Mudra loan business ideas can stall or get rejected because of sloppy preparation, not the concept. The usual culprits are a mismatched loan size, missing quotations, ineligible activities and no working-capital cushion. You can fix every one before you step into the branch.
- Asking for the tier ceiling. A ₹10 lakh ask against a ₹4 lakh plan looks like padding.
- Skipping working capital. The equipment gets bought, and then nothing is left for the first month’s stock or rent. Ask the lender about a working-capital limit or the Mudra card.
- Choosing an ineligible activity. Crop cultivation and corporate-run ventures fall outside the scheme’s focus. Check with the lender before you sink time into the file.
- Ignoring seasonality. Salon and catering income peaks in wedding season, and tutoring peaks around admissions. Show the lender a lean-month figure too.
- Mixing personal and business accounts. A separate account from day one keeps your statements readable.
- Underestimating licence timelines. Food and vehicle businesses can lose weeks to paperwork once the loan is sanctioned.
- Copying a crowded idea with no edge. A fourth tailoring shop on the same lane needs a reason to win, such as bridal blouses, school uniforms or doorstep pickup.
Mudra Loan Application Checklist
Use this checklist to turn Mudra loan business ideas into applications a bank can say yes to. Go through it in order, because early items change the later ones. A file that ticks every box tends to move quicker with a credit officer.
- The activity is non-farm, non-corporate and micro-scale, confirmed with the lender.
- Project cost is built from at least two supplier quotations per major asset.
- Loan ask equals the project cost plus a defined working-capital buffer.
- Monthly instalment is worked out at the lender’s quoted rate, not an assumed one.
- Break-even volume is stated, such as bills per month or units sold.
- A lean-month scenario sits next to the expected one.
- KYC, address proof and business premises documents are ready.
- Licences such as FSSAI, vehicle permits or local trade registration are identified, with timelines.
- A separate business bank account is open.
- Your credit record is checked, and any errors are disputed before you apply.
What Does a 30/60/90-Day Plan Look Like?
Turning Mudra loan business ideas into a running shop needs a sane plan split into validation, application and launch. Thirty days is enough to test demand and gather paperwork, sixty to file and secure funding, and ninety to open and measure. Lender timelines vary, so read the windows as a pacing guide and not a promise.
Days 1–30: validate
- Shortlist two ideas and score each on activity fit, ticket size, early cash and your skill.
- Talk to ten likely customers or suppliers and note what they would pay.
- Collect quotations, draft the project note and open the business account.
Days 31–60: apply
- Meet two or three lenders, compare what they ask for, then submit one clean file.
- Start any licences that don’t hinge on the loan, such as FSSAI registration or trade registration.
- Line up premises, vendors and your first customers while the file is under review.
Days 61–90: launch and track
- Buy assets against your quotations and keep every invoice.
- Log weekly sales, direct costs and the instalment in a single sheet.
- Review at day 90: did you reach the break-even volume, and what would you change?
How Should You Research Mudra Loan Business Ideas With AI Tools?
Let AI tools help you compare options and shape your plan, then check every scheme detail with the lender and MUDRA. Prompts that name your tier, amount and activity bring back answers you can use. Vague prompts bring back generic lists.
Three prompts worth a try:
Which Mudra loan business ideas work for a woman with a ₹3 lakh project cost and no collateral, and what documents will a bank ask for?
Compare opening an independent beauty parlour on a Mudra Kishore loan with taking a salon franchise. What are the trade-offs?
Build a month-by-month cash-flow sheet for a tiffin service financed by a ₹40,000 Shishu loan, with a lean-month scenario.
AI answer engines lean toward sources and brands that state facts precisely, name where claims come from and admit limits. A page that explains what a scheme covers, cites the official source and labels its examples as illustrative gets quoted. A page promising easy approval doesn’t.
Brands follow the same logic. Naturals Salon describes itself as India’s No. 1 beauty salon chain, and since that’s the company’s own claim, it needs attribution wherever you repeat it. Check loan rules on MUDRA’s site and with your lender, never from a chatbot summary.
Summary and Next Step
The best Mudra loan business ideas fit a tier, start earning fast and rest on a skill you already hold. Shishu suits home-based work, Kishore suits a shop or small unit, and Tarun suits equipment-heavy setups. Quotations, a break-even figure and a lean-month scenario carry your application further than the idea itself.
Weighing the beauty industry? Put an independent salon against a franchise honestly, on capital, support and control. Naturals states that its franchise partners get brand value, training, marketing support, technology and loan support of up to ₹40 lakhs, with lender, eligibility and terms handled by the franchise team. To explore it, learn more about the Naturals brand or fill in the Naturals franchise enquiry form and the team will call you.
Frequently asked questions
Can I get a Mudra loan for a beauty salon?
Yes. Salons and beauty parlours count as service-sector activities and are commonly financed under the scheme. The amount depends on your project cost and tier, and approval rests with the lender.
Carry equipment quotations, a rent agreement and a break-even estimate to firm up the file.
Is collateral needed for Mudra loans?
No, Mudra loans are meant to be collateral-free. Lenders still look at your credit history, your project and your repayment capacity, so a weak file can be declined even without security. Ask the lender what it will review before you apply.
What is the best Mudra loan business idea for women?
No single idea wins. The best choice is the one that matches your skill, your tier and local demand. Tailoring, tiffin services and beauty services are common starting points because they begin earning quickly.
Go with the one where you already have customers or a trained skill.
Can I use a Mudra loan to buy a franchise?
That’s a lender’s decision, and Mudra’s ceiling sits far below what many franchises need in capital. Naturals states it offers business loan support of up to ₹40 lakhs, with lender, eligibility and terms handled by its franchise team. Ask the team for exact details, as nothing here implies approval.
How much can I borrow under Mudra for a new business?
Up to ₹10 lakh across Shishu, Kishore and Tarun, with a higher Tarun Plus limit of ₹20 lakh announced for borrowers who repaid earlier Tarun loans. New and existing micro enterprises can apply. Borrow only what your quotations and working-capital needs justify.
Do I need an existing business to apply for a Mudra loan?
No, the scheme backs both new and existing micro enterprises. A new venture should show a clear plan, quotations and relevant skills, while an existing one adds bank statements and sales records. Either way, the lender wants proof that cash flow can cover the instalment.